Most Michigan med spa owners have thought hard about the clinical side of a bad reaction. Far fewer have opened their policy to see what it would actually pay for.
One bad outcome starts three processes at once. Michigan’s licensing bureau runs its own. The patient’s attorney runs another. Your insurance runs a third, and that one has its own deadlines and a few clauses that decide whether you are covered or arguing. Here is how the third one plays out, using a composite example rather than any real practice, and what it means for your commercial and small business insurance.
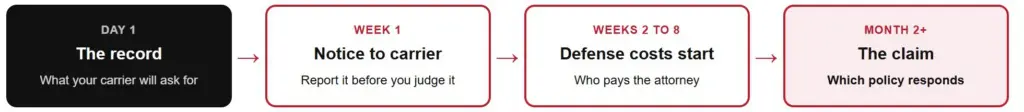
Day one: the record your carrier will ask for
Your medical director handles the clinical response. Stabilize the patient and escalate to emergency care if the situation calls for it.
Then write it down the same day. Product, lot number, dose, injection sites, how the patient looked before and after, and what you told them.
That chart is not just a medical record. It is the document your carrier uses to decide whether to defend the claim or question it, and it is what your defense attorney builds from. Notes written the same day carry weight that notes written three weeks later do not. A thin chart is the most common reason a defensible claim turns expensive.
Week one: the notice clock starts
An unhappy patient has options. A bad review. A chargeback. A call to an attorney. A complaint to the state. Plenty of people do more than one.
Your first insurance decision comes before any of that becomes a lawsuit. When do you tell your carrier?
Almost always now. Most policies require prompt notice of a claim or of a circumstance that could become one. Late notice is a common reason a covered claim turns into a fight with your own carrier. Waiting until you know whether the complaint has merit is exactly the wrong instinct.
Claims-made, occurrence, and why the reporting date matters
Medical professional liability is commonly written on a claims-made basis. A claims-made policy covers claims reported while it is in force. An occurrence policy covers incidents that happened while it was in force, whenever the claim shows up.
That difference is not academic. On a claims-made policy, an incident in October that you report the following March may land outside the policy that was in force when it happened.
Two terms control this. The retroactive date is how far back your policy reaches. Tail coverage, sometimes called an extended reporting period, lets you report a claim after the policy ends. If you ever change carriers, sell the practice, or close it, tail coverage is the difference between protection and a gap. Ask what yours costs before you need it.
Weeks two to eight: who pays for the lawyer
If the patient filed a complaint with Michigan’s Bureau of Professional Licensing, an investigation opens and records get requested. That part worries owners most, but the insurance question is narrower. Who is paying the attorney?
General liability and professional liability respond to claims for damages. A licensing investigation is not a claim for damages. It is a regulatory proceeding, and a standard liability policy may not respond to it at all.
Many professional liability policies add a regulatory or licensing defense grant. It usually carries its own sublimit, a stated amount per proceeding separate from your main limit, and those amounts are often modest. Without it, the fees come out of your pocket, and they start long before anyone has filed a lawsuit.
Ask two questions. Is licensing defense included, and what is the sublimit?
Where your product came from, and why your policy cares
Somewhere in the records phase, a question catches practices off guard. Can you show that every unit you used came from an authorized source?
Federal law treats med spas as dispensers. The FDA said so in an April 2026 warning letter to a Texas medical spa, the first it has sent to a dispenser under the Drug Supply Chain Security Act. The finding was a gap between how much Botox the practice bought through authorized channels and how much it put into patients. That standard applies to Michigan practices the same way.
The insurance consequence is the part worth knowing. Policies commonly exclude claims arising from products obtained outside approved channels, or from treatments performed outside the scope of a license. A sourcing gap can turn a covered treatment claim into a denied one. Your purchase records are not only compliance paperwork. They are part of what keeps the claim covered.
Which policy responds
Professional liability covers the treatment itself: the injection, the laser setting, the clinical judgment. General liability covers injury that is not treatment related, like a fall in the lobby. That distinction decides which policy answers, which limit applies, and which deductible you pay.
Two gaps show up constantly. The first is the medical director who carries personal malpractice coverage while the owners assume it reaches the practice. Often it does not, because the practice is a separate entity and usually needs its own.
The second is structural. Michigan requires that medical practices be owned by physicians, so non-physician owners generally run a management services organization alongside the practice. That means two entities and two sets of exposures. A policy naming only one can leave the other uncovered, so check the named insured against your formation documents.
Why your general liability limit matters more in Michigan now
For decades, a Michigan business could defeat most slip and fall claims with the open and obvious defense. If a hazard was plain to see, the case usually ended before trial.
That changed in 2023, when the Michigan Supreme Court decided Kandil-Elsayed v. F & E Oil. Whether a hazard was obvious no longer ends the case. It is now a comparative fault question for a jury, weighed against whether the business took reasonable care.
For a med spa, the icy walkway outside your Rochester or Troy suite is a live general liability exposure in a way it was not three years ago. Your winter maintenance records matter more than they used to, and so does the size of your limit. The same shift is changing how Michigan property owners think about coverage.
Do defense costs come out of your limit?
This is the most useful question on the declarations page, and most owners have never asked it.
Policies handle defense two ways. Some pay defense costs outside the limit, so the full limit stays available to settle. Others pay defense inside the limit, which the industry calls eroding or wasting. On a one million dollar policy with defense inside the limit, spending three hundred thousand on defense leaves seven hundred thousand to resolve the claim.
Both structures are legitimate, but they are not the same product, and two quotes showing the same limit can be worth very different amounts.
While you are asking, check who controls settlement. Some policies let the carrier settle without your agreement, and others give you a say but add a hammer clause that caps your coverage if you refuse a settlement the carrier recommends. For a practice that lives on reputation, that clause is worth reading before an offer is on the table.
Which coverage responds to what
| Coverage | Responds to | What to check |
| Professional liability | The treatment itself | Claims-made or occurrence, retroactive date, whether it covers the entity |
| General liability | Injury not tied to treatment | Your limit, given Michigan’s 2023 premises liability change |
| Licensing defense | Attorney fees in a state proceeding | Whether it is included, and the sublimit |
| Cyber liability | Exposed patient records | Notification costs, which run high on health data |
| Commercial umbrella | Claims past the primary limit | Whether it sits above professional liability or only general liability |
What a claim does to your next renewal
Claims follow the practice. Carriers price on claim history, and aesthetic practices with an open claim can be harder to place, not just more expensive. The market for Michigan med spa coverage is thinner than it is for a retail or office risk, so fewer options means less room to shop your way out of a bad year.
That creates a bad temptation: keep a small matter quiet to protect the record. Resist it. An unreported claim that surfaces later risks the coverage entirely, which is far worse than a rate increase.
Ask your agent now what a claim of a given size would likely do to your renewal. That is a five minute conversation today and a much harder one later.
What to check on your policy this week
- Confirm claims-made or occurrence, and find the retroactive date
- Find out whether defense costs erode the limit or sit outside it
- Ask whether licensing defense is included, and what the sublimit is
- Confirm professional liability covers the practice entity, not just the medical director
- Match the named insured against every entity in your ownership structure
- Ask what tail coverage would cost if you changed carriers or sold
- Review your general liability limit against Michigan’s current premises liability standard
- Save your agent’s direct contact so notice goes out the day a letter arrives
Talk through your coverage before you need it
If you run a med spa in Rochester, Rochester Hills, Troy, or anywhere in Oakland County, the right day to learn what your policy covers is any day but the day something goes wrong. Marcus Schirr Insurance Group works with small businesses across Southeast Michigan to compare what is on the policy against what the practice actually faces.
Contact Marcus Schirr Insurance Group or call 248.464.8749.